- A Practical Procurement Transformation Roadmap - September 8, 2026
- Purchase Requisitions and Purchase Orders Compared - September 8, 2026
- Spend Under Management Formula and Improvement Strategy - September 8, 2026
A parcel audit ROI model estimates realized credits and avoidable charges net of provider fees, software, implementation, and internal effort. Results depend on contract rules, shipment mix, claim windows, and recovery realization.
Which financial outcomes should a parcel audit ROI calculator estimate?
In practical terms, eligible parcel spend sets the operating boundary, identified credit identifies what the organization is trying to protect or improve, and recovery rate provides the facts needed to test the opportunity. Provider fee should not be calculated or classified until the population, period, currency or unit, exclusions, and decision owner are explicit.
Decision boundary
- Recoveries: Use recoveries to define the boundary and decision consequence; retain the dated source and explain why the evidence is sufficient.
- Avoided charges: Use avoided charges to define the boundary and decision consequence; retain the dated source and explain why the evidence is sufficient.
- Provider fees: Use provider fees to define the boundary and decision consequence; retain the dated source and explain why the evidence is sufficient.
- Internal costs: The definition should set out internal costs with a documented baseline, unit, period, inclusions, formula, rounding rule, and sensitivity range. Finance should be able to reproduce the calculation for internal costs from the evidence retained for this definition.
- Net benefit: The definition should set out net benefit with a documented baseline, unit, period, inclusions, formula, rounding rule, and sensitivity range. Finance should be able to reproduce the calculation for net benefit from the evidence retained for this definition.
Evidence and application
A practical application makes the boundary visible. An illustrative scenario begins with eligible spend, estimates error opportunities from a sample, applies conservative recovery and timing assumptions, subtracts every cost, and tests downside, expected, and upside cases. The decision file should distinguish observed facts from accepted assumptions, preserve rejected alternatives, and name the evidence that would reopen the decision about internal cost.
The main failure is a decision built on the wrong population or evidence, not a shortage of terminology. Applying a case-study percentage to total parcel spend ignores scope, exclusions, carrier rules, invoice quality, and provider economics. A reviewer should be able to trace eligible parcel spend to internal cost, identify the accountable owner, and see how the expected result will be verified after implementation.
Documentation can remain proportionate to eligible parcel spend. Low-value and reversible identified credit work may use a lighter record, whereas material, regulated, safety-critical, or continuity-sensitive work needs deeper validation. Either treatment of identified credit must be justified by evidence that fits the actual conditions of this decision.
Which shipment, invoice, error-rate, fee, recovery, implementation, and timing inputs belong in the model?
The operating sequence converts eligible parcel spend into payback period through explicit handoffs. At each identified credit stage, the record needs an input, responsible role, acceptance test, and usable output; an activity list without those four items is uncontrolled.
Operating sequence
1 — Eligible parcel spend. The workflow should reconcile eligible parcel spend across the manifest, invoice, contract, tracking record, and effective-dated carrier rules. Only exceptions involving eligible parcel spend that are confirmed and credited in this workflow count as realized recovery.
2 — Identified credit. Use identified credit to connect the input to a named output and acceptance gate; retain the dated source and explain why the evidence is sufficient.
3 — Recovery rate. The workflow should set out recovery rate with a documented baseline, unit, period, inclusions, formula, rounding rule, and sensitivity range. Finance should be able to reproduce the calculation for recovery rate from the evidence retained for this workflow.
4 — Provider fee. Use provider fee to connect the input to a named output and acceptance gate; retain the dated source and explain why the evidence is sufficient.
5 — Internal cost. The workflow should set out internal cost with a documented baseline, unit, period, inclusions, formula, rounding rule, and sensitivity range. Finance should be able to reproduce the calculation for internal cost from the evidence retained for this workflow.
6 — Realized net saving. The workflow should set out realized net saving with a documented baseline, unit, period, inclusions, formula, rounding rule, and sensitivity range. Finance should be able to reproduce the calculation for realized net saving from the evidence retained for this workflow.
7 — Payback period. The workflow should set out payback period with a documented baseline, unit, period, inclusions, formula, rounding rule, and sensitivity range. Finance should be able to reproduce the calculation for payback period from the evidence retained for this workflow.
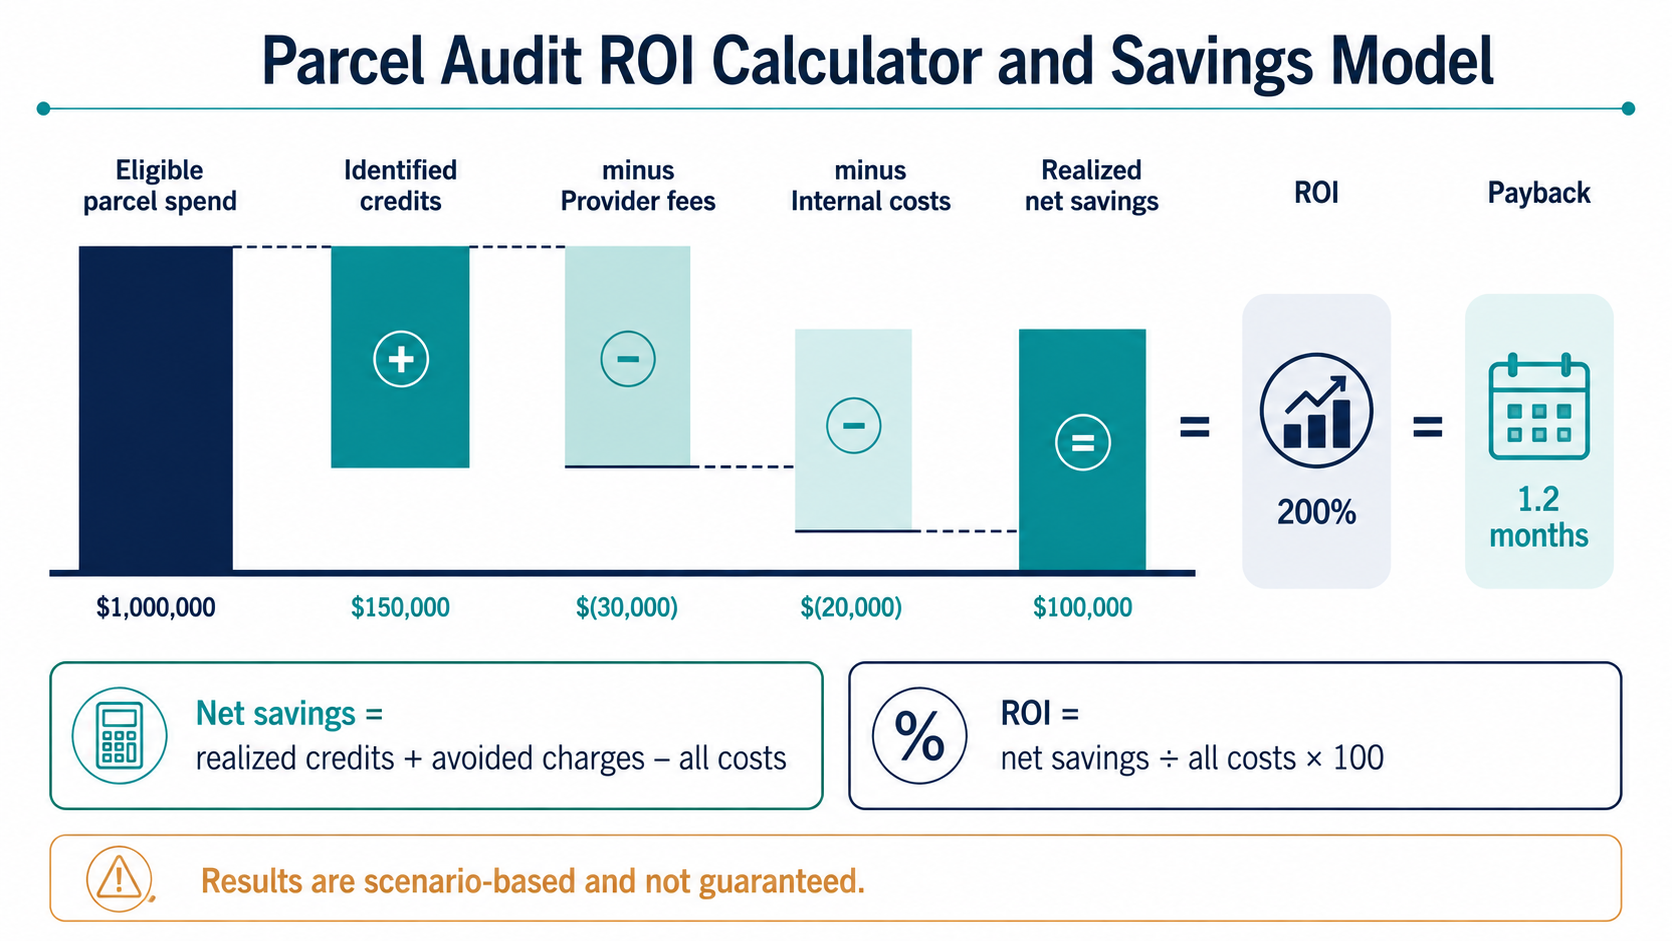
Figure: Parcel Audit ROI Calculator and Savings Model — evidence, decisions, owners, and outputs across the operating flow.
Handoffs and exceptions
One practical sequence works as follows: An illustrative scenario begins with eligible spend, estimates error opportunities from a sample, applies conservative recovery and timing assumptions, subtracts every cost, and tests downside, expected, and upside cases. The sequence stops when evidence for identified credit is incomplete instead of passing ambiguity downstream. Rework tied to recovery rate is coded to its producing stage, separating capacity constraints from definition, approval, supplier-response, or data-quality defects.
Exceptions need their own route. Urgency around eligible parcel spend may compress timing, but it does not erase authority, requirement clarity, commercial comparison, receipt, or post-award evidence. The person accountable for realized net saving defines who can authorize a deviation, which minimum checks remain, and when work returns to the standard path.
An illustrative annual model can start with $60,000 of realized credits, not merely identified exceptions. If provider fees are $15,000, recurring software and internal labor are $9,000, and one-time implementation cost is $6,000, first-year total cost is $30,000 and net benefit is $30,000. ROI is 100%. If recurring net cash after variable and operating cost is $3,000 per month and the $6,000 implementation cost is paid at launch, simple payback on that upfront investment is two months.
How should parcel-audit case studies be normalized before they inform expected returns?
A usable analytical layer makes recovery rate, provider fee, and internal cost comparable. Options for provider fee must share one population, period, unit, currency basis, inclusion rule, and scenario logic; otherwise even a precise score can support the wrong choice.
Measurement and comparison
- Case evidence by shipper profile: Use case evidence by shipper profile to make the evidence comparable across options; retain the dated source and explain why the evidence is sufficient.
- Audit scope: Use audit scope to make the evidence comparable across options; retain the dated source and explain why the evidence is sufficient.
- Time period: Use time period to make the evidence comparable across options; retain the dated source and explain why the evidence is sufficient.
- Baseline: Use baseline to make the evidence comparable across options; retain the dated source and explain why the evidence is sufficient.
- Gross recovery: Use gross recovery to make the evidence comparable across options; retain the dated source and explain why the evidence is sufficient.
Sensitivity testing should concentrate on variables capable of changing internal cost: volume, mix, timing, price, utilization, recovery, risk, or threshold assumptions as applicable. Showing a base case, downside case, and provider fee break point reveals whether this choice is robust or depends on one optimistic input.
Interpretation and control
The analytical owner should lock the source version, retain calculation logic, and document overrides. A second reviewer reconciles the output to eligible parcel spend and tests whether the criteria for internal cost were applied as approved. If a small assumption shift changes the result, the recommendation about provider fee is conditional rather than certain.
Normalization field | What to capture | Why it matters | Acceptable comparison |
Shipper profile | Spend, shipments, services, zones, package mix | Error opportunity depends on mix | Similar operating population |
Audit scope | Charges and service failures tested | Excluded rules change the result | Same test library |
Economics | Gross credits, provider fees, internal cost, net realized value | Gross recovery is not net benefit | Same cost boundary |
Timing | Invoice period, claim window, credit date | Identified value may not realize | Same realization horizon |
Which sensitivity, realization, payback, and reconciliation tests make the savings estimate decision-ready?
Control design begins with the failure that matters: Applying a case-study percentage to total parcel spend ignores scope, exclusions, carrier rules, invoice quality, and provider economics. The response should combine prevention near eligible parcel spend with detection in workflow, transaction, supplier, invoice, or performance data, and name the owner of correction.
Preventive safeguards
- Conservative: Use conservative to pair prevention with an exception and escalation path; retain the dated source and explain why the evidence is sufficient.
- Expected: Use expected to pair prevention with an exception and escalation path; retain the dated source and explain why the evidence is sufficient.
- Upside scenarios: Use upside scenarios to pair prevention with an exception and escalation path; retain the dated source and explain why the evidence is sufficient.
- Reconcile sample invoices: The control design should reconcile reconcile sample invoices across the manifest, invoice, contract, tracking record, and effective-dated carrier rules. Only exceptions involving reconcile sample invoices that are confirmed and credited in this control design count as realized recovery.
- Check contract terms: Use check contract terms to pair prevention with an exception and escalation path; retain the dated source and explain why the evidence is sufficient.
Detection and correction
A material internal cost exception needs four records: observed condition, expected value, authorized disposition, and closure evidence. Trend internal cost exceptions by root cause instead of treating each as an isolated task. Repeated defects in internal cost or realized net saving indicate that process, master data, contract, training, or supplier action needs redesign.
Controls over realized net saving must remain proportionate to this decision. Too many realized net saving approvals can push users outside the process, while automatic approval can conceal bad master data. Monitor cycle time with compliance, sample approved and rejected cases, and test whether corrective actions changed payback period rather than merely closing a ticket.
How can Hubzone Depot's Parcel Audit Services validate savings opportunities using actual invoice data?
Hubzone Depot's Parcel Audit Services page describes an invoice-review service that examines carrier charges, discounts, service failures, and potential credits. This business case must use the shipper's own records and agreement terms; an exception affecting internal cost becomes savings only after eligibility is confirmed and the credit is reconciled to a later invoice.
Service fit
- Defined scope: The request evaluated can be bounded using eligible parcel spend and a clear completion criterion.
- Comparable evidence: The buyer can compare returned information against recovery rate on the same unit and time basis.
- Decision authority: An internal owner remains accountable for internal cost and any exception or award related to this decision.
- Operational follow-through: Receiving, payment, credit, or performance evidence can confirm payback period after action under the approved approach.
- Proportionate route: The effort matches value, urgency, complexity, regulatory exposure, and reversibility.
Intake and buyer control
An intake package should include carrier invoices, executed agreements, shipment manifests, package dimensions and weights, tracking events, accessorial detail, claims, and credited invoices. Resolve missing fields in the intake before comparing quotes or audit findings, because different assumptions about eligible parcel spend, service, timing, quantity, or eligibility can make similar-looking results non-comparable.
The next step is to review Hubzone Depot's Parcel Audit Services page and request only the information needed to test the eligible parcel spend use case. The buyer documents the evaluation method in advance, retains its own approvals, and confirms implementation or credit evidence before reporting an outcome.
Conclusion: What should shippers remember when interpreting parcel audit ROI?
The practical conclusion is to connect the original need to an implementable, testable decision. That requires the boundary for eligible parcel spend, the evidence behind recovery rate, the approval criteria for internal cost, and the owner who will verify payback period.
Implementation priorities
- Define: In practice, state the population, period, inclusions, exclusions, and authority for eligible parcel spend.
- Verify: In practice, reconcile recovery rate to a dated source and distinguish facts from assumptions.
- Decide: Apply internal cost consistently and preserve the rejected alternative.
- Implement: Assign realized net saving and specify the required acceptance evidence.
- Review: Measure payback period after implementation and reopen the decision when a material condition changes.
Start with a limited invoice sample, reconcile identified items to credited invoices, and approve scale only when net realized benefit is traceable. The recommendation is strongest when the current requirement, policy or contract, source dates, assumptions, and implementation capacity are verifiable. A material change affecting eligible parcel spend, market availability, regulation, carrier rules, supplier capability, or data quality can change the conclusion.
Decision rule and sources
A final review of this decision should not rely on one score. The internal cost record should explain why the chosen path is acceptable, identify residual risk and its owner, and set the next review date or trigger. The resulting record turns payback period into evidence for the next decision instead of forcing the organization to reconstruct its reasoning from email.